This post is about my own story and mentions my own book, The Mortgage Playbook. This is my own book, written and sold by me. When you buy through a link on this page, you are buying directly from the author.
My phone stopped feeling like a phone. It felt like a debt-collector alarm clock. The debt collectors called day and night. Texts came in that I would not open. Letters landed in my mailbox and went straight into the trash, unopened.
I was not being stubborn. I was embarrassed. I was tired. So I hid — hoping that if I did not answer, it would all just go away. It did not.
The Day I Stopped Running From Debt Collectors
One day I got mad enough to fight back. First, I paid a credit company, thinking they knew the game. Slim to no results. So I did the thing I had been avoiding: I ordered my three credit reports — the free ones you can get once a year — and faced the truth, line by line.
Lo and behold, there were old accounts sitting on those reports with brand-new dates on them, like somebody had wound the clock back up and started the whole collection over again.
What You Don’t Know Can Hurt You
Here is what nobody tells you: in a lot of states, if you pay even one dollar on an old account, you can restart their clock to come after you. An account that was five years old wakes right back up. That is how money gets made off what you don’t know.
And it does not stop with the collectors. You can have money in the bank and still watch every door close. With bad credit, the banks turn you down — or they approve you and charge you a high interest rate that bleeds you every single month. That is the bracket you stay stuck in until you take control of your credit.
Credit is the key to a better life. Trust me on that. You can run from the collectors, but you cannot hide from the number. It follows you for life.
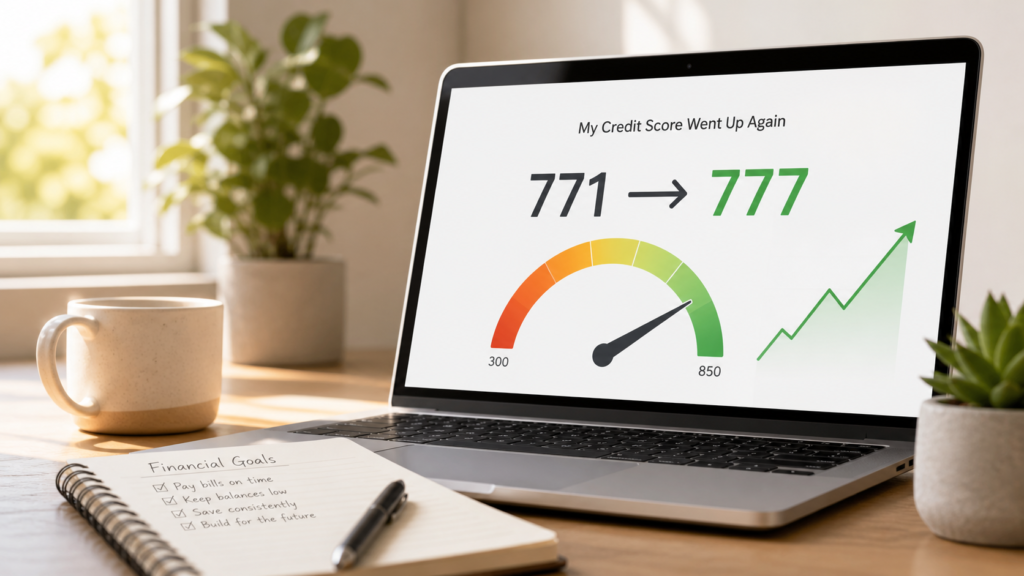
So I stopped running. I faced every line on those reports, and I took my control back from the banks and the collectors. My credit score is now 777 — and I bought my own home. The full game plan I used is inside my book. This story is just the reason I wrote it.
Watch Marcus Tell It
Words on a page are one thing — hearing the story told out loud is another. Marcus tells it the way it happened:
▶ Watch Marcus tell it — “I Stopped Running” — on HustleTube, my own video platform.
Keep Reading
- Delete collections and rebuild your credit — the system I used
- How I rebuilt my credit to buy a home
- My credit score went up again — 771 to 777
The full game plan is inside my book: The Mortgage Playbook — $27
Frequently Asked Questions
Can debt collectors call you day and night?
Collectors are not supposed to call at all hours — the rules generally limit calls to between 8 in the morning and 9 at night, your local time. But when several collectors are chasing you at once, it can sure feel like day and night. That is exactly how it felt for me.
Can paying a little on an old debt restart it?
In a lot of states, yes — even a small payment on an old debt can restart the clock for collectors to sue you over it. The rules are different in every state, which is why knowing the game matters before you send anyone a dollar.
Can disputing remove accurate negative marks from my credit report?
Generally, no. Accurate negative information usually stays on your report for its full reporting period, and disputing alone does not remove it. Mistakes can be disputed — but real debts have to be faced, negotiated, and paid, the way I did it.
Where is the full game plan you used?
It is inside my book, The Mortgage Playbook — my own story and the game plan I followed to rebuild my credit and buy my home. You can get it at freebiebro.org/store.